
For casino operators, player fund segregation means keeping money owed to players separate from the money used to run the business. It should prevent deposits and unpaid winnings from becoming a source of working capital. But opening a second bank account is only part of the job: account ownership, payment-provider arrangements, reserve calculations and insolvency treatment all matter.
The practical objective is to know what players are owed, identify the assets backing those obligations and understand who can access those assets if something goes wrong. This guide explains how to build that structure across fiat payments, crypto wallets and a white label casino platform.
What player fund segregation actually protects
Segregation creates a boundary between player money and operating money. Marketing bills, payroll, software fees and affiliate commissions belong on the operating side of that boundary, not in the reserve backing player balances.
A workable arrangement has three distinct layers:
| Layer | What it establishes | What it does not establish by itself |
|---|---|---|
| Accounting separation | Which balances and transactions belong to players | That matching assets exist outside the operating account |
| Asset separation | Where the backing bank deposits or digital assets are held | That players have priority over creditors |
| Legal protection | Ownership, permitted use and treatment on insolvency | Immediate access under every possible failure scenario |
A casino can have clean ledger labels without holding enough money. It can also hold enough money in a separate account while leaving players exposed to the operator’s insolvency.
Segregation and insolvency protection are related, but they are not interchangeable. Operators need evidence for both rather than treating an account name or dashboard balance as proof.
Separate accounts do not automatically mean bankruptcy protection
The legal effect of an arrangement depends on the jurisdiction, account documentation and rights attached to the money. A trust, where available and properly established, can produce a different outcome from an ordinary bank account simply labeled “player funds.”
For Great Britain, the Gambling Commission’s LCCP condition 4.1.1 on segregation of funds sets out separate client bank account requirements for licensees within its scope. Its condition 4.2.1 on disclosure of protection of customer funds addresses customer-facing disclosure of insolvency protection. These are distinct obligations, not a single guarantee that every player will recover their balance.
Before describing funds as protected, obtain a documented assessment covering the account holder, beneficial ownership, creditor access and the bank’s contractual rights. Review whether set-off, security interests or provider liens could affect the assets.
Player fund segregation must therefore be designed for the actual licensed entity and operating markets. A structure accepted for one license cannot simply be copied across every brand or jurisdiction. Confirm the applicable requirements with gambling counsel and the relevant banking or custody partners.
Define exactly which player obligations need backing
A reserve calculation is only reliable if its liability definition is complete. Start with a written policy mapping every relevant balance type to its treatment under the applicable rules.
Cash deposits and settled winnings credited to player accounts are central categories. Pending withdrawals also need explicit treatment: moving money out of an available balance must not make the obligation disappear before payment is completed.
Other categories require closer analysis:
- Restricted bonuses: Distinguish promotional credits from cash entitlements and define what happens when wagering conditions are satisfied.
- Open wagers and unsettled games: Document the treatment of stakes, possible payouts and interrupted rounds rather than assuming the displayed wallet balance captures everything.
- Jackpots and tournament prizes: Establish which entity owes the prize and whether a supplier or network genuinely funds that obligation.
- Disputed or blocked balances: Record the legal basis for any exclusion; a withdrawal review does not automatically extinguish the player’s claim.
Avoid counting the same withdrawal twice if it appears in both the player ledger and a payment queue. Equally, do not count it zero times because each system assumes the other owns the liability.
Finance, compliance and engineering should approve this mapping together. A balance label chosen by a software developer is not, on its own, a legal classification.
Map the entire custody chain
Identify the entity that owes the player
In a white label arrangement, the brand, license holder, platform provider and merchant account holder may be different businesses. Contracts should identify which entity owes the player balance and which entity holds the backing assets.
A platform can display a wallet and process transactions without being the legal custodian. Conversely, outsourcing custody does not automatically transfer the operator’s regulatory obligations.
Check every intermediary
Trace the route from deposit initiation through the payment gateway, processor, bank or crypto custodian. Identify where money is held, whether it is available for withdrawal and what happens if an intermediary fails.
Processor balances deserve particular attention. Money shown as “settled” in a provider dashboard may still be subject to settlement delays, rolling reserves, chargebacks or contractual deductions. Do not assume every payment-provider receivable qualifies as an eligible backing asset.
Keep operating liquidity separate
Player fund segregation should not depend on next week’s deposits covering today’s withdrawals. Maintain operating capital for fees, refunds, chargebacks and business expenses separately from the required player reserve.
Any release of surplus funds should follow a verified calculation and documented approval. Gross gaming revenue alone is not proof that an equivalent amount can safely leave the protected structure.
Calculate coverage using eligible assets, not headline balances
A useful control calculation is:
Coverage surplus or shortfall = eligible backing assets minus covered player liabilities.
“Eligible” is the critical word. Exclude assets that the applicable framework does not recognize, and avoid counting assets twice as they move between a processor and a bank.
Consider this illustrative fiat-only snapshot. Assume pending withdrawals have already been removed from available player balances, and the processor receivable is not eligible under this operator’s approved policy.
| Item | Amount | Treatment |
|---|---|---|
| Available player cash balances | $1,020,000 | Covered liability |
| Pending withdrawals | $80,000 | Additional covered liability |
| Confirmed balance in the designated client bank account | $1,040,000 | Eligible backing asset |
| Processor receivable awaiting settlement | $90,000 | Excluded from eligible assets |
Covered liabilities total $1,100,000. Eligible assets total $1,040,000, producing a $60,000 shortfall. The processor receivable does not remove that shortfall simply because it is expected to arrive tomorrow.
The response should include an immediate escalation, a halt to discretionary reserve releases and a top-up from operator-owned funds, subject to the applicable rules. Investigate the cause rather than merely patching the number.
A management buffer can absorb timing differences, but it is not a substitute for a correct liability calculation. Establish a daily reconciliation baseline and add intraday checks when transaction volumes or payment events warrant them.
How crypto changes the segregation problem
A dedicated blockchain address makes transactions visible. It does not, by itself, establish beneficial ownership, restrict the custodian’s contractual rights or determine how assets will be treated in insolvency.
For crypto-ready solutions, document who controls the keys, who legally owns the assets and whether the custody agreement permits lending, pledging or other reuse. If assets sit in an omnibus wallet, establish how the operator’s entitlement is recorded and independently verified.
Player fund segregation also needs a currency policy. A dollar-denominated player liability backed by a stablecoin creates depegging and redemption risk. A token-denominated liability requires enough deliverable units of that token, plus a separate plan for network fees and withdrawal liquidity.
Valuation haircuts and internal buffers may help manage risk, but they do not make an otherwise ineligible asset permissible. Whether crypto can count toward required backing depends on the relevant rules and approved structure.
Hot and cold wallet allocation introduces another distinction: assets may exist but be unavailable for prompt withdrawals. Track both reserve coverage and accessible liquidity.
A merchant custodial wallet can support safekeeping, but the word “custodial” is not evidence of bankruptcy remoteness. Review the contract and legal structure, not just the product description.
Turn the policy into enforceable operating controls
Reconcile assets and liabilities on the same basis
Use a common cutoff time and consistent transaction statuses across the player ledger, payment providers and bank or wallet records. Separate confirmed balances from estimates, disputed amounts and funds in transit.
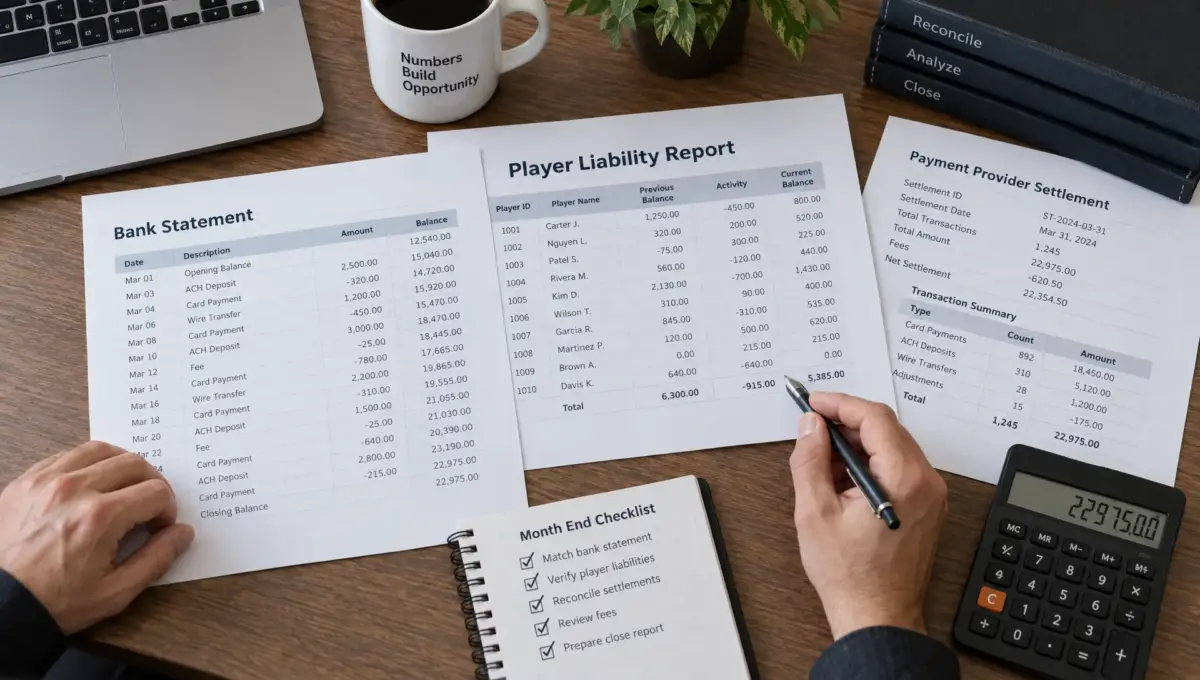
The mechanics of matching the casino ledger, PSP records and bank statements support this process, but the segregation policy determines which reconciled amounts actually count toward coverage.
Record exceptions with an owner and resolution deadline. An unexplained difference is not an acceptable permanent reconciling item.
Restrict transfers and reserve releases
Separate the ability to calculate a surplus from the authority to move it. Apply dual approval to reserve releases and restrict destination accounts so routine payment access cannot become unrestricted access to player funds.
These controls should align with the operator’s broader treasury approval rules and segregation of duties. The specific objective here is preventing an authorized business payment from drawing on assets required for players.
Retain evidence that survives staff changes
Keep the liability calculation, source balances, valuation method, approvals and exception history for each reporting period. Record why an asset was included or excluded, especially where provider terms or legal advice affect eligibility.
Management reporting should show coverage, available withdrawal liquidity and unresolved exceptions separately. A single green status can conceal a fully funded reserve that cannot make payments promptly.
Test failures before they become player losses
Player fund segregation needs testing beyond a normal trading day. Run scenarios involving a processor freeze, a bank outage, a major jackpot payout and an unexpected withdrawal surge.
For crypto operations, add custodian failure, stablecoin depegging and loss of access to a signing device. Measure whether the operator can establish ownership, calculate liabilities and access sufficient eligible assets without relying on new deposits.
Also test the failure of the operator itself. Could an insolvency practitioner identify the relevant accounts, player entitlements and supporting records? Are the documents held somewhere accessible if the usual finance administrator or platform provider is unavailable?
Give each scenario a named response owner, an escalation route and a recovery procedure. Where a test exposes a shortfall or an unclear ownership claim, resolve the underlying issue before treating the structure as dependable.
What to ask a platform or custody provider
Procurement should distinguish software functionality from legal protection. A provider may offer multi-currency wallets and detailed transaction reports while leaving account ownership and safeguarding arrangements entirely to the operator.
Ask for evidence against specific questions:
- Which legal entity holds each bank account or wallet, and which entity owes the player?
- Can reporting distinguish cash, restricted bonuses, pending withdrawals and unsettled obligations without duplication?
- What records demonstrate the operator’s entitlement to assets held in pooled custody?
- Which controls restrict reserve transfers, and can the operator export approvals and transaction history?
- What happens to funds, records and operational access if either party fails or the contract ends?
Evaluate the answers with finance and legal teams, not only the integration team. Open APIs and a customizable backoffice can support the control design, but they cannot replace appropriate account agreements or jurisdiction-specific legal analysis.
Frequently asked questions
Is player fund segregation the same as keeping 100% of balances in reserve? No. Full backing concerns the amount held against liabilities. Segregation concerns how those assets are separated, controlled and legally treated. An operator may satisfy one objective while failing the other.
Can player deposits be used to pay operating expenses? A properly designed segregation policy keeps assets required to cover player obligations unavailable for operating expenses. Only a verified surplus should be considered for release, subject to applicable rules and approvals.
Do pending withdrawals remain part of the reserve calculation? They should not disappear merely because a withdrawal request has been submitted. Define the point at which payment discharges the obligation, and ensure the amount is counted once until then.
Does a white label casino provider handle segregation automatically? Not necessarily. Responsibilities depend on the licensed operating model, contracts and custody arrangements. Verify who holds the funds and who remains accountable rather than assuming the platform covers both.
Build fund protection into your platform requirements
Spinlab offers an iGaming platform with fiat and crypto payment support, merchant custodial wallets, a customizable backoffice and open API integration. Those capabilities can form part of an operator’s financial infrastructure, while the legal segregation structure requires its own assessment.
When discussing your casino platform requirements with Spinlab, bring your liability definitions, custody model and reporting requirements. Establish what the technology must support before launch, not after the first reserve discrepancy.
